TL;DR

Get business pricing on tech for your team
- Business-only prices and quantity discounts
- Tax-exempt purchasing
- Multiple users, one account, clear invoices
In a post titled “I’m not convinced the AI bubble exists,” Matteo Raso argues that current AI investment may be justified by rapidly growing revenue and future adoption. His case depends on estimates and projections, and the post acknowledges that the industry’s debt and spending commitments are difficult to measure.
Matteo Raso argues in a new essay that the AI industry’s huge spending does not, by itself, show that its valuations are unsustainable, pointing to growing revenue, possible future demand and the prospect that data-center construction costs will eventually ease. The essay is an opinionated analysis, not an independent financial audit, and it says the industry’s complex financing makes its total commitments difficult to establish.
Raso’s central distinction is between the cost of building AI infrastructure and the cost of operating AI services once that infrastructure is in place. He argues that data centers are largely one-time investments, and that spending could fall after facilities are built. He also says companies could curb some expenses quickly by limiting free access to products or pausing costly research, although debt and long-term commitments would be harder to reduce.
The essay cites an estimate that AI companies have made at least $3 trillion in spending commitments, alongside an estimate of $1.9 trillion already spent, for a combined figure of around $5 trillion. Raso stresses that the totals are hard to pin down because financing is arranged through complex vehicles. The source does not provide a methodology for those industry-wide estimates, so they should be treated as figures cited by the author rather than settled accounting.
Raso also points to reported revenue figures in Anthropic’s S-1 filing: $41 million in 2023, $386 million in 2024, $4.585 billion in 2025 and $16.3 billion in the first six months of 2026. He says the filing indicates the company earned $2.08 for each $1 of compute. These figures concern one company and particular reporting periods; they do not establish that the whole AI sector is profitable or that revenue growth will continue at the same pace.
The Case for Ongoing AI Demand
The debate matters because large investments in AI infrastructure connect technology-company valuations with data-center construction, borrowing and the expectations of investors. If revenue and paid use grow enough to support those investments, today’s spending could be part of a long-term expansion. If they do not, companies may face pressure to cut costs, delay projects or meet debt obligations with less room to maneuver.
Raso’s argument also highlights a gap between present-day use and potential future applications. He expects wider use of AI in programming, mathematics and administrative work in fields such as law and medicine, and mentions autonomous vehicles as another area of development. These are forecasts about adoption and economic effects, not evidence that all those uses are already widespread or profitable.
For readers, the essay is a counterargument to claims that a market downturn is inevitable. It does not establish that AI stocks are fairly valued, or that the sector can avoid losses. Its practical implication is narrower: high spending and uncertain returns are reasons to examine company finances, but they are not, on their own, proof that the entire industry is a bubble.
Products Worth Considering
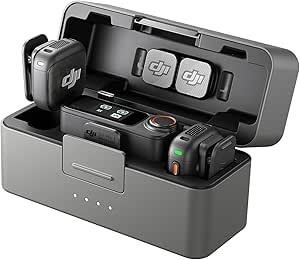
DJI Mic 3 (2 TX + 1 RX + Charging Case) Wireless Microphone

Amazon Kindle Paperwhite (2024, 12th Generation), 16 GB, 7-Inch Display, Black

Bose QuietComfort Wireless Noise-Cancelling Headphones, Twilight Blue
As an affiliate, we earn on qualifying purchases.
Investment, Revenue and Valuations
The term “AI bubble” refers to the possibility that company valuations and investment have risen beyond what future earnings can support. That is a question about expectations as well as current performance: companies can be growing quickly and still be overvalued if prices assume even faster growth or durable profits that do not arrive.
Raso compares a hypothetical $5 trillion of costs repaid over 20 years—$250 billion a year—with Alphabet’s reported revenue of nearly $162 billion in 2019, which he adjusts to about $213 billion for inflation. He presents this as rough arithmetic, not a forecast of the AI sector’s future revenue. The comparison is also between an industry-wide financing estimate and one company’s revenue in a past year, rather than a like-for-like measure of ability to repay debt.
The essay further cites Anthropic’s reported share-based loss of $72 billion in the first six months of 2026, which it links to shares due to lenders and an estimated company valuation of $1 trillion. The source describes this as a way creditors could receive equity instead of cash. That does not make the obligation disappear: the value of the shares and the terms of the financing matter, and the supplied material does not detail those terms.
Debt and Demand Remain Unclear
The essay does not establish the industry’s total debt, contractual commitments or future cash flows. Raso says financing structures make commitments hard to calculate, and his $5 trillion estimate and 20-year repayment example are not presented with enough supporting detail to verify them from the supplied source material.
It is also unclear whether Anthropic’s reported revenue and compute economics are representative of other AI companies. The essay predicts broad adoption and rising use, but does not quantify how much customers will pay, how quickly businesses will deploy the tools, or whether savings and productivity gains will outweigh operating and infrastructure costs. Its claim that AI could become far more widely consumed remains a forecast.
The source text offers a point-in-time argument rather than a complete assessment of market valuations. It does not provide comparable financial data for other major AI firms, an independent review of the cited filings, or a full accounting of the risks attached to debt, leases and future infrastructure spending.
The Financial Test Ahead
The argument’s central test will be whether paid demand and revenue continue to grow as AI companies carry the costs of data centers, compute and financing. Later company filings and disclosures may show whether operating economics improve, how commitments are structured and whether revenue gains translate into cash available for investment and debt payments.
For now, Raso’s essay puts forward a case against treating a market correction as inevitable: AI infrastructure spending could slow after construction, while adoption expands. Whether that scenario holds will depend on measurable results—customer use, company margins, financing terms and returns on infrastructure—not on the growth forecasts alone.
Key Questions
What is Matteo Raso arguing?
Raso argues that heavy AI spending does not automatically mean the industry is in a bubble. He says infrastructure costs may ease after data centers are built, while revenue and demand could keep growing.
Does the essay prove that AI companies are profitable?
No. It cites figures from Anthropic’s S-1 filing and an estimate of revenue per dollar of compute, but those figures do not establish profitability across the industry or account for every financing and infrastructure cost.
How much AI spending does the essay cite?
Raso cites estimates of at least $3 trillion in commitments and $1.9 trillion already spent, or around $5 trillion combined. He says the figures are difficult to determine because of complex financing, and the source material does not provide a full methodology.
What does Raso say could make AI demand grow?
He points to possible uses in programming, mathematics, administrative work in professional fields and autonomous vehicles. These are expected applications in his argument, not proof that widespread adoption or profits have already arrived.
Source: matteoraso.github.io